UPI has already changed the way India pays.
Today, we use UPI for tea, groceries, petrol, online shopping, mobile recharge, subscriptions, food delivery, cab rides, local stores and even small roadside purchases. It is fast, simple and almost invisible in daily life.
Now, the next big shift is UPI Credit Lines.
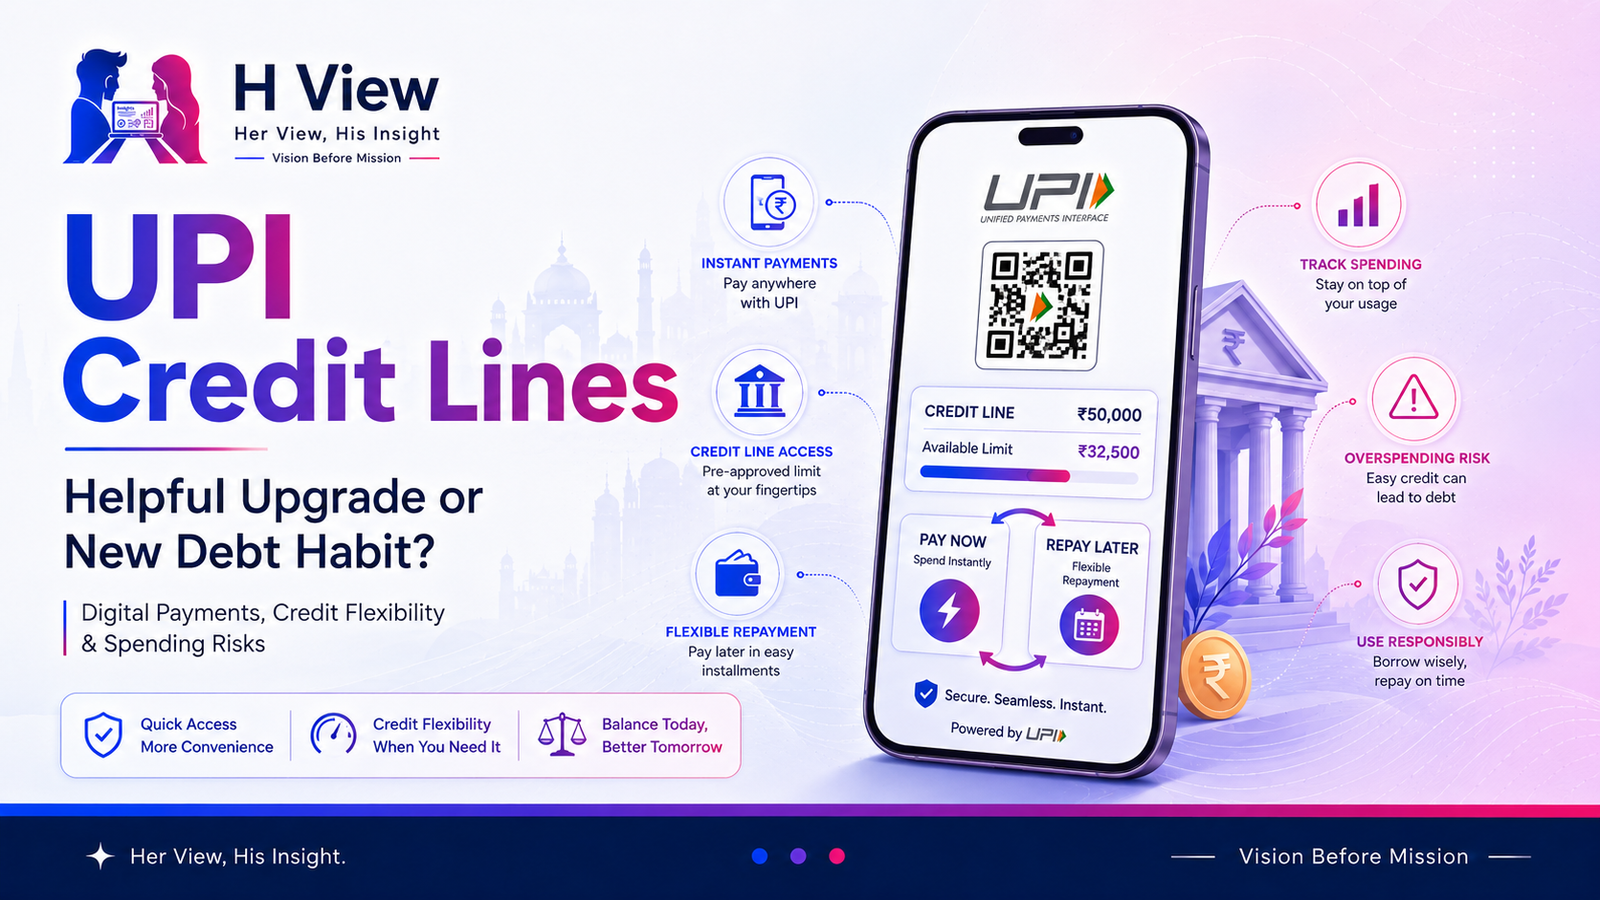
Instead of paying only from your bank account balance, users may be able to pay through a pre-approved credit line linked to UPI.
That sounds useful. But it also raises an important question:
Will UPI Credit Lines make payments more flexible, or will they quietly create a new debt habit?
At H View, our practical view is simple:
Credit is useful only when it is planned. When credit becomes too easy, spending discipline becomes even more important.
What Are UPI Credit Lines?
UPI Credit Line is a feature that allows users to access a pre-sanctioned credit line from a bank and use it for UPI payments.
NPCI describes Credit Line on UPI as a product that empowers individuals and businesses to access pre-sanctioned credit lines from banks, especially for low-ticket, high-volume retail loans.
In simple words, it works like this:
- Your bank approves a credit limit.
- You link that credit line to UPI.
- You can pay merchants using that credit line.
- You repay the used amount later as per the bank’s terms.
This is different from normal UPI, where money is deducted directly from your bank account.
With UPI Credit Line, you are not using your current balance. You are using approved credit.
How Does Credit Line on UPI Work?
The exact process may vary depending on your bank and UPI app, but the basic idea is simple.
A user may:
- Open a supported UPI app.
- Choose the option to link a credit line.
- Select the issuing bank.
- Link the available pre-approved credit line.
- Set or use a UPI PIN for payments.
- Pay supported merchants using the credit line.
NPCI’s UPI product page explains that UPI itself is an instant payment system built over IMPS infrastructure and allows instant transfers between bank accounts. Credit Line on UPI builds on this UPI experience, but adds bank-approved credit access to the payment flow.
That means the payment experience may feel similar to UPI, but the money source is different.
Normal UPI:
Bank account balance → MerchantUPI Credit Line:
Bank-approved credit limit → Merchant → Repay laterThis difference matters a lot.
Why UPI Credit Lines Are Important in India
UPI is already huge in India.
NPCI’s UPI statistics show that in May 2026, UPI had 720 banks live, with 23,201.93 million transactions and transaction value of ₹29,90,424.21 crore.
When such a widely used payment system starts adding credit access, the impact can be big.
UPI Credit Lines can affect:
- Daily purchases
- Small merchant payments
- Digital lending
- Retail credit
- Consumer spending
- Small business cash flow
- Bank-led credit products
- Fintech innovation
This is why the topic is important. It is not just another payment feature. It can change how people borrow and spend.
How UPI Credit Line Is Different From Normal UPI
Normal UPI is simple: you pay from money already available in your bank account.
UPI Credit Line is different because it allows payment from a credit facility approved by the bank.
| Feature | Normal UPI | UPI Credit Line |
|---|---|---|
| Money source | Bank account balance | Bank-approved credit limit |
| Repayment | No repayment needed | Repayment required later |
| Spending control | Limited by account balance | Limited by credit limit |
| Risk | Lower debt risk | Higher debt risk if misused |
| Best use | Daily payments | Planned short-term credit needs |
| User mindset | “I am paying” | “I will pay later” |
The biggest change is psychological.
When money leaves your bank account immediately, you feel the cost. When it becomes credit, the cost may feel delayed.
That can be helpful or risky depending on the user.
UPI Credit Line vs Credit Card
UPI Credit Line may feel similar to a credit card, but the experience is different.
A credit card is a separate card-based credit product. UPI Credit Line works through UPI payment apps and QR-based merchant payments.
| Feature | Credit Card | UPI Credit Line |
| Payment method | Card / online card payment | UPI app / QR payment |
| Merchant acceptance | Card network acceptance | UPI-supported merchants |
| Physical card | Usually yes | Not necessarily |
| User experience | Card-based | UPI-based |
| Credit provider | Bank / issuer | Bank-approved credit line |
| Risk | Overspending if misused | Overspending if misused |
The important point is this:
Both are credit products. Both need repayment discipline.
UPI Credit Line may feel easier because users are already comfortable with UPI. That convenience can become a strength or a weakness.
Benefits of UPI Credit Lines
UPI Credit Lines can be useful when used carefully.
1. Helpful During Short-Term Cash Gaps
Sometimes salary is delayed, payment from a client is pending, or there is an emergency expense before money is available.
A small credit line can help manage short-term needs.
2. Useful for Small Merchants
Small business owners may use credit for inventory, daily business expenses or working capital needs, depending on the bank’s product terms.
3. No Need for a Physical Card
Users may not need to carry a card. Payments can happen through UPI apps.
4. Familiar UPI Experience
People already know how to scan and pay. That makes adoption easier.
5. Bank-Led Credit Access
Since the credit line is pre-sanctioned by banks, it can bring more structured credit access compared to informal borrowing.
6. Better for Planned Credit
If users understand repayment terms and use it only for planned expenses, it can be a useful financial tool.
Risks of UPI Credit Lines
The same convenience can also create risks.
1. Easy Credit Can Increase Spending
UPI already makes payments frictionless. Adding credit can make spending even easier.
A research study on UPI spending behavior found that about 75% of surveyed participants reported increased spending due to UPI, with many connecting this to the intangible nature of digital payments and reduced spending guilt.
If normal UPI already increases spending for many people, credit on UPI needs even more caution.
2. Users May Forget It Is Borrowed Money
Because the payment flow may feel like normal UPI, users may not mentally separate bank balance spending from credit spending.
That can create a “buy now, worry later” habit.
3. Interest and Charges Can Add Up
Credit products may include interest, fees, penalties or repayment conditions depending on the bank.
Users must read the terms carefully.
4. Small Payments Can Become Big Debt
A few small credit-based payments may not feel serious.
But repeated purchases can add up:
₹199 + ₹349 + ₹499 + ₹799 + ₹999 = a repayment burden later5. Missed Payments Can Hurt Credit Health
If repayment is not handled properly, it may affect credit discipline and future borrowing ability.
6. Fraud and Digital Safety Matter
UPI fraud and digital payment scams remain a concern in India. Recent reports continue to show misuse through fake UPI IDs and fraudulent payment setups, making user awareness important.
With credit involved, users should be even more careful.
Who Should Use UPI Credit Lines?
UPI Credit Lines may be useful for people who are financially disciplined.
It may suit:
- Salaried users with stable income
- Small business owners with predictable cash flow
- Users who understand repayment dates
- People who need short-term payment flexibility
- Users who can track expenses properly
- People who avoid impulse buying
It can be helpful when used for genuine needs, not random spending.
Who Should Avoid UPI Credit Lines?
Some users should be careful or avoid it.
Avoid or delay using UPI Credit Lines if:
- You already overspend through UPI
- You do not track monthly expenses
- You often buy impulsively
- You have existing unpaid loans
- You miss payment due dates
- You do not understand interest or charges
- You treat credit like extra income
- You use shopping apps out of boredom
Credit is not free money. It is future repayment.
If spending discipline is weak, UPI Credit Line can become risky.
How to Use UPI Credit Lines Responsibly
If you choose to use UPI Credit Line, use it with rules.
1. Set a Monthly Limit
Do not use the full credit limit just because it is available.
Set your own personal limit below the approved limit.
2. Use It Only for Planned Expenses
Use credit for planned purchases, not random cravings or impulse shopping.
3. Track Every Credit Payment
Maintain a simple list:
Date
Amount
Purpose
Repayment due date
4. Check Charges Before Using
Before using the credit line, check:
- Interest rate
- Repayment date
- Late fees
- Processing charges
- Grace period if any
- Merchant restrictions
- Bank terms
5. Avoid Multiple Credit Products
Do not mix credit cards, BNPL, personal loans and UPI credit without clear tracking.
6. Repay Before Due Date
Repayment discipline is more important than access to credit.
7. Do Not Use It for Lifestyle Inflation
If you cannot afford something without credit, ask whether it is truly necessary.
Smart Rule for UPI Credit Lines
Use this simple H View rule:
Use UPI Credit Line for timing problems, not spending problems.A timing problem means:
I need to pay today, but confirmed money is coming soon.A spending problem means:
I want to buy more than I can afford.Credit can help with timing. It cannot fix overspending.
Her View
From the user experience side, UPI Credit Line can feel very convenient.
It removes the stress of low bank balance during urgent moments. It also works through a payment system people already understand. That makes it feel simple and familiar.
But this is also the danger.
If credit feels exactly like normal UPI, users may forget that they are borrowing. For daily users, this can quietly change spending behavior.
Convenience is good, but only when the user stays aware.
His Insight
From the practical finance side, UPI Credit Lines are powerful because they combine two things: instant payments and instant credit access.
That can improve credit availability, especially for low-ticket transactions and small business needs.
But the risk is behavioral.
UPI made payments easier. Credit Line on UPI may make borrowing easier.
This means banks, apps and users must focus on transparency, repayment clarity, spending alerts and responsible usage.
The feature is useful, but it should not normalize unnecessary debt.
H View Recommendation
UPI Credit Lines are a helpful upgrade for disciplined users, but risky for impulsive spenders.
Use it if you:
- Understand the terms
- Track your spending
- Repay on time
- Use credit only when needed
- Avoid unnecessary purchases
Avoid it if you:
- Already overspend
- Do not track money
- Miss due dates
- Treat credit as extra income
- Use apps for impulse shopping
At H View, our recommendation is simple:
Use credit as a tool, not as a habit.
FAQs
A UPI Credit Line is a pre-approved credit facility from a bank that can be linked to UPI and used for eligible merchant payments.
No. Normal UPI uses your bank account balance. UPI Credit Line uses a bank-approved credit limit that must be repaid later.
Not exactly. Both are credit products, but a credit card is card-based, while UPI Credit Line works through UPI apps and QR payments.
It can be safe if used through official apps and banks, but users must protect their UPI PIN, avoid fraud, read bank terms and track repayments.
Yes, it can. Since UPI payments already feel easy, adding credit can encourage users to spend more if they do not set limits.
It is better suited for financially disciplined users who understand repayment terms and need short-term credit flexibility.
People who overspend, miss due dates, do not track expenses or already have multiple debts should be cautious.
Final View
UPI Credit Lines can become a useful financial feature in India.
They can help users manage short-term cash gaps, support small purchases and bring bank-led credit into a familiar UPI experience.
But the same convenience can also create a new debt habit if users are not careful.
At H View, our final view is simple:
UPI Credit Line is helpful when used with discipline. It becomes dangerous when users treat credit like extra money.